There's a simple truth about taxes: the difference between earning well and keeping well is almost entirely planning. Most people think about taxes once a year, in a short, anxious window around their filing deadline. The people who save the most treat taxes as a year-round strategy, making small adjustments all through the year so that come filing time, they're collecting what the law allows instead of scrambling to minimize a bill that's already been decided.
The single highest-impact move for most households is maximizing retirement contributions — and doing it through the right vehicle. If your employer offers a 401(k) match, contributing at least enough to capture the full match is free money: a 5% match is a guaranteed 5% return on that contribution, no market performance required. Beyond the match, Traditional 401(k) and Traditional IRA contributions reduce your taxable income today, which can be worth thousands if you're in a high bracket now and expect to be in a lower one in retirement. Roth accounts flip the math — you pay tax now and everything grows and withdraws tax-free — and in 2026 many advisors blend both to balance today's relief with tomorrow's flexibility.
If you have access to a Health Savings Account, it's the most tax-advantaged account in the American financial system, and one of the most underused. HSA contributions are tax-deductible, money grows tax-free, and withdrawals for qualified medical expenses are tax-free — and here's the trick most people miss: withdrawals for non-medical expenses are allowed after age 65 without penalty, just taxed. That effectively makes the HSA a triple-tax-advantaged retirement vehicle disguised as a health account. Fund it for your actual expected medical costs, and let the rest compound.
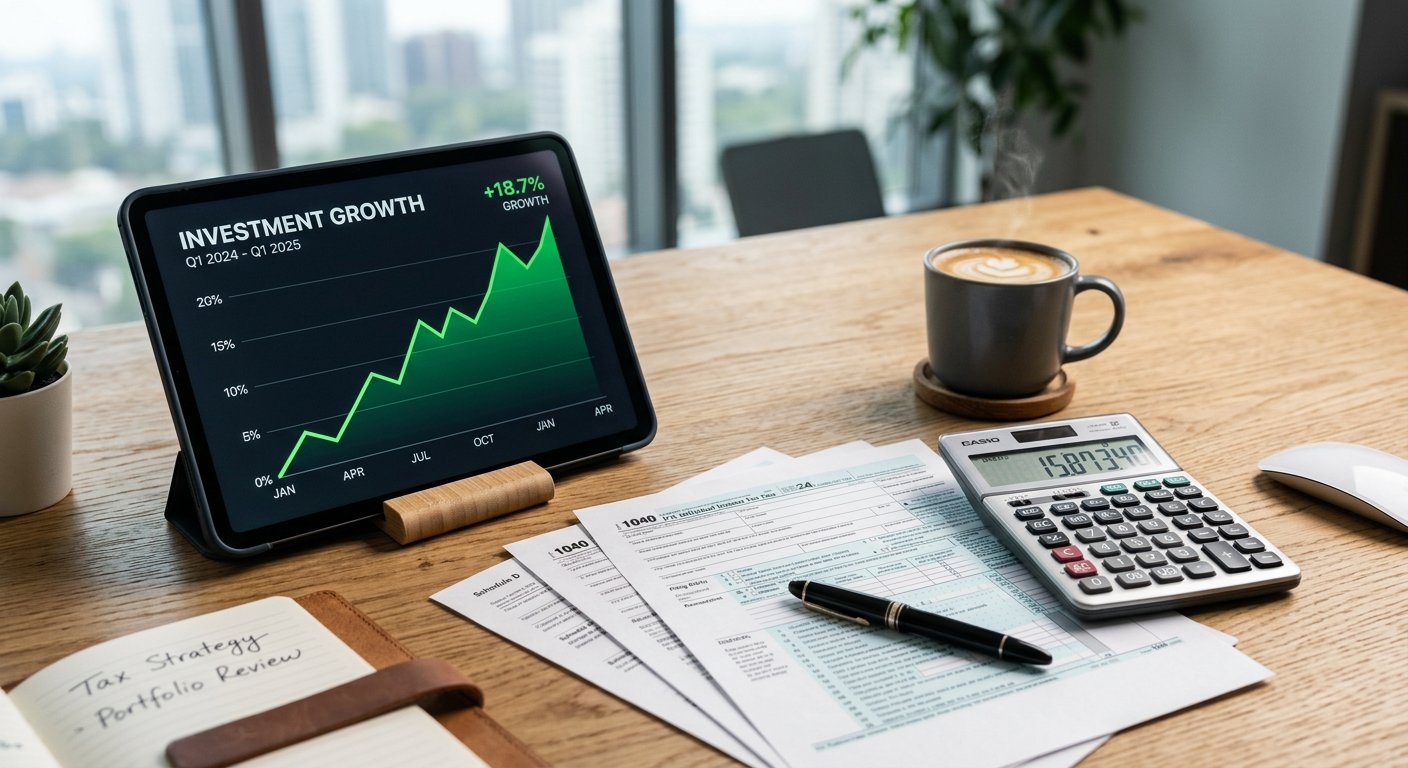
If you hold an investment portfolio, two techniques can meaningfully soften your tax bill. The first is tax-loss harvesting: when an investment has lost value, selling it lets you offset capital gains with the loss, and up to $3,000 of ordinary income per year. The second is asset location — deciding which account each asset lives in. High-growth, taxable assets like individual stocks belong in tax-advantaged accounts (IRA, 401(k)) where their gains never get taxed, while tax-efficient investments like index funds do fine in regular brokerage accounts. Rebalancing these placements across your accounts once a year can save a household several hundred to several thousand dollars in taxes annually.
Education expenses carry their own set of powerful tools. The 529 plan is the workhorse: contributions grow tax-free, withdrawals for qualified education expenses are tax-free, and the annual gift tax exclusion means you can fund a 529 for a grandchild without any gift tax paperwork. Even better, if you don't end up needing the money for education, the account can be transferred to another family member or the original account owner without penalty. Starting a 529 early — even with small contributions — lets compounding do the heavy lifting while the tax shelter does the quiet work.
Business owners and the self-employed have the deepest well of legal deductions, but also the most to lose by missing them. The home office deduction, vehicle use, health insurance premiums, and retirement plan contributions through a SEP-IRA or Solo 401(k) can all shrink taxable income substantially — but only when documented properly. The self-employed also face quarterly estimated tax payments, and the two classic mistakes are paying too little (triggering an underpayment penalty) or misjudging Q4 when the year's income jumps. Working with an advisor who projects your full-year income quarterly — rather than reacting to the IRS in April — is the difference between a tax bill that stings and one that was planned for.
Charitable giving deserves planning too, not just generosity. Donating appreciated stock instead of cash lets you skip the capital gains tax on the appreciation and deduct the full fair market value. For those who can't itemize in a given year, the standard deduction still allows a modest charitable deduction even when taking it — a change that has made small, consistent giving far more valuable than it was a decade ago. And bundling your charitable gifts strategically across a year or two can keep more of your itemized deductions above the standard deduction threshold in the years that matter most.
Timing income and expenses is the final, often-overlooked lever. If you're near the boundary between tax brackets, a few thousand dollars of late-year income — a bonus, a sale of an asset, catching up on 401(k) contributions — can tip you from one bracket into another. Similarly, if you know a big deduction is coming (a home purchase, a large medical bill, a charitable gift), accelerating or deferring it into the right year changes your effective tax rate. These moves are small individually, but for anyone earning six figures or running a business, the compounding effect over a decade is genuinely significant.
The through-line in every one of these strategies is the same: they only work when they're decided in advance, by someone who tracks the rules as they change year to year. Tax law in 2026 is not the same as 2024, and the same deductions and limits that worked for you two years ago may have shifted. Rather than trying to be your own compliance department, put a professional in your corner one to two times a year — one sitting in January to set the year's plan, one in late December to make final adjustments. That's the difference between a tax refund that surprises you and a tax bill that was never allowed to surprise you in the first place.
Want a Personal Tax Plan?
Our tax advisory team builds your year-round strategy — deductions, retirement accounts, estimated payments, and year-end adjustments — so your return is a formality, not a fire drill.
Book a Free Tax Review